deimos1969
New member
Hi everyone,
Like many readers of The Poor Swiss, I have spent a lot of time analyzing the classic Swiss wealth allocation dilemma: **Voluntary 2nd Pillar (Pensionskasse) buy-in vs. investing directly into a global equity ETF (like VT)**.
While voluntary buy-ins offer an immediate tax deduction at your top marginal income tax rate (typically 25% to 42%), the actual net advantage is surprisingly nuanced once you consider:
1. Marginal income tax saved today vs. discounted capital withdrawal tax (Kapitalbezugssteuer) at retirement.
2. The opportunity cost hurdle: low guaranteed pension interest (~1.25% to 2.5%) vs. compounding global equities in CHF.
3. The 3-year lock-in rule (Art. 79b BVG) preventing lump-sum withdrawals.
4. Correctly deciphering all the technical figures on the annual Vorsorgeausweis.
As an actuary working in Switzerland, I wanted a clean, transparent, and privacy-first tool to model this exact math, so I developed **SmartPensionApp** for iOS.
━━━━━━━━━━━━━━━━━━━━━
**WHAT THE APP DOES:**
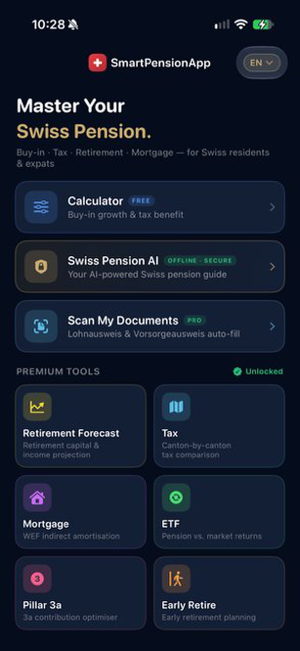
• **Free 2nd Pillar Buy-In Calculator:**
Compares gross buy-in against your real marginal tax rate. Models year-by-year compounding and net-of-tax capital after cantonal withdrawal taxes across all 26 Swiss cantons. Generates clean PDF reports.
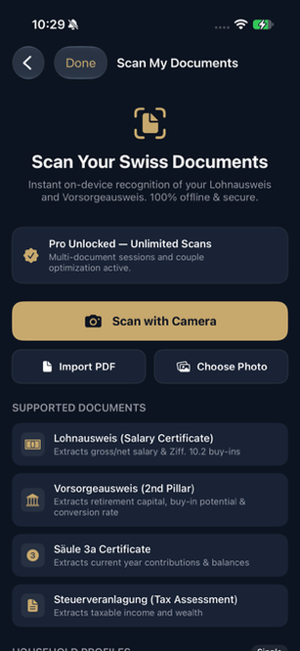
• **On-Device Document Scanner (Apple Vision OCR):**
Point your iPhone camera at your Vorsorgeausweis or Lohnausweis. It automatically extracts your retirement capital, conversion rate (Umwandlungssatz), salary, and maximum buy-in potential on-device without manual typing.
• **ETF Opportunity Cost Modeling:**
Calculates your personal breakeven horizon between taking the immediate tax deduction vs. compounding 100% in a global ETF portfolio (factoring in 15% irrecoverable dividend WHT and TER).
• **WEF Mortgage & Early Retirement:**
Indirect vs. direct amortisation tax alpha, AHV 21 gap years, and early retirement reduction penalties.
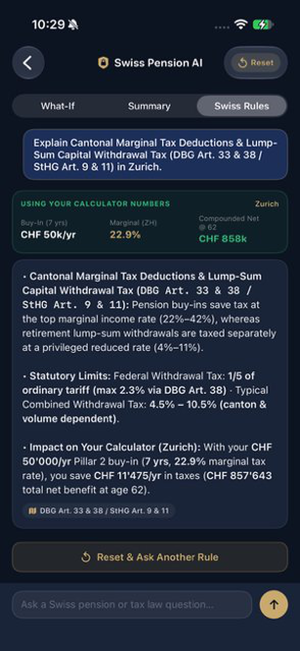
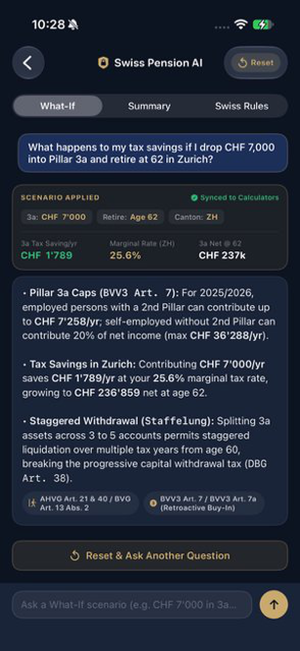
• **On-Device Swiss Pension AI Coach:**
Ask natural language What-If questions (e.g. "What happens if I contribute CHF 15k before year-end and retire early at 62?") with direct Swiss statutory law references (BVG, BVV3, DBG, StHG).
━━━━━━━━━━━━━━━━━━━━━
**PRIVACY & ON-DEVICE ARCHITECTURE:**
Since pension certificates contain sensitive salary and personal data, the app is built to be **100% on-device**:
• No user accounts or logins required.
• Zero telemetry, analytics, or tracking.
• No cloud servers: All OCR document parsing and calculations run locally on your iPhone using Apple's Neural Engine. Nothing leaves your phone.
━━━━━━━━━━━━━━━━━━━━━
The core **2nd Pillar Buy-In Calculator is completely free to use**.
App Store Link:

 apps.apple.com
I would love to get your thoughts, critique on the calculation logic, and any edge cases you think I should build into the model.
Thanks for any feedback!
Like many readers of The Poor Swiss, I have spent a lot of time analyzing the classic Swiss wealth allocation dilemma: **Voluntary 2nd Pillar (Pensionskasse) buy-in vs. investing directly into a global equity ETF (like VT)**.
While voluntary buy-ins offer an immediate tax deduction at your top marginal income tax rate (typically 25% to 42%), the actual net advantage is surprisingly nuanced once you consider:
1. Marginal income tax saved today vs. discounted capital withdrawal tax (Kapitalbezugssteuer) at retirement.
2. The opportunity cost hurdle: low guaranteed pension interest (~1.25% to 2.5%) vs. compounding global equities in CHF.
3. The 3-year lock-in rule (Art. 79b BVG) preventing lump-sum withdrawals.
4. Correctly deciphering all the technical figures on the annual Vorsorgeausweis.
As an actuary working in Switzerland, I wanted a clean, transparent, and privacy-first tool to model this exact math, so I developed **SmartPensionApp** for iOS.
━━━━━━━━━━━━━━━━━━━━━
**WHAT THE APP DOES:**
• **Free 2nd Pillar Buy-In Calculator:**
Compares gross buy-in against your real marginal tax rate. Models year-by-year compounding and net-of-tax capital after cantonal withdrawal taxes across all 26 Swiss cantons. Generates clean PDF reports.
• **On-Device Document Scanner (Apple Vision OCR):**
Point your iPhone camera at your Vorsorgeausweis or Lohnausweis. It automatically extracts your retirement capital, conversion rate (Umwandlungssatz), salary, and maximum buy-in potential on-device without manual typing.
• **ETF Opportunity Cost Modeling:**
Calculates your personal breakeven horizon between taking the immediate tax deduction vs. compounding 100% in a global ETF portfolio (factoring in 15% irrecoverable dividend WHT and TER).
• **WEF Mortgage & Early Retirement:**
Indirect vs. direct amortisation tax alpha, AHV 21 gap years, and early retirement reduction penalties.
• **On-Device Swiss Pension AI Coach:**
Ask natural language What-If questions (e.g. "What happens if I contribute CHF 15k before year-end and retire early at 62?") with direct Swiss statutory law references (BVG, BVV3, DBG, StHG).
━━━━━━━━━━━━━━━━━━━━━
**PRIVACY & ON-DEVICE ARCHITECTURE:**
Since pension certificates contain sensitive salary and personal data, the app is built to be **100% on-device**:
• No user accounts or logins required.
• Zero telemetry, analytics, or tracking.
• No cloud servers: All OCR document parsing and calculations run locally on your iPhone using Apple's Neural Engine. Nothing leaves your phone.
━━━━━━━━━━━━━━━━━━━━━
The core **2nd Pillar Buy-In Calculator is completely free to use**.
App Store Link:
SmartPensionApp App - App Store
Download SmartPensionApp by Edgar Flores Parra on the App Store. See screenshots, ratings and reviews, user tips, and more apps like SmartPensionApp.
apps.apple.com
I would love to get your thoughts, critique on the calculation logic, and any edge cases you think I should build into the model.
Thanks for any feedback!