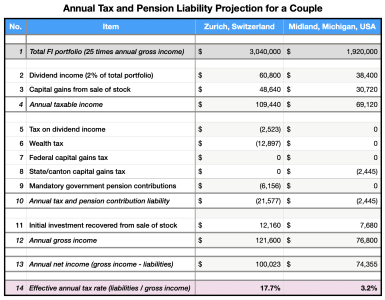
The "Swiss FIRE Paradox" Poor Swiss blog post inspired me to study the impact of taxes and pension on geoarbitrage destinations. For this case study I compared the FIRE scenarios for a married couple living in Zurich Switzerland versus Midland, Michigan, USA.
The cost of living and taxes vary significantly in the USA depending on the state and city. New York City is one of the most expensive cities in the world and makes even Zurich look relatively affordable. For this projection I chose to compare Midland to Zurich. Midland is a small, low-cost city in the state of Michigan in the United States.
Conclusions
What about government pensions?
AHV pension income for the Zurich couple and Social Security income for the Midland couple were deliberately excluded from this projection.
Unfortunately the government pension schemes in many countries including Switzerland and the USA are already facing severe deficits and will need major reforms in the upcoming years to pay pension liabilities for their large aging populations.
I believe that it highly probable that Switzerland, the USA, and many other countries will be forced to implement an assets test for old age pensions. Australia has already implemented an assets test. By definition most financially independent people are millionaires and their high assets will make them ineligible to receive government pensions.
Some people in the USA financial independence community completely ignore the possibility of receiving Social Security payments when they reach traditional retirement age. They just assume their assets will make them ineligible.
It would be prudent in my opinion for financially independent Swiss people to not consider AHV payments as part of their FIRE numbers because probably in 20 years they will not be eligible anyways. I view my AHV wage deductions as a tax that supports elderly Swiss retirees but definitely not something that I will ever get any benefit from.
The cost of living and taxes vary significantly in the USA depending on the state and city. New York City is one of the most expensive cities in the world and makes even Zurich look relatively affordable. For this projection I chose to compare Midland to Zurich. Midland is a small, low-cost city in the state of Michigan in the United States.
No. | Notes and Sources |
| General | The scenario is applied to a married couple in both locations. All values are in USD. For Swiss taxes and pension contributions the following currency exchange rate was used: 1.00 CHF = $1.21 USD |
| 1 | The FIRE number is assumed to be 25 times annual gross income. This definitely needs to be adjusted to actually be 25 times annual net income which was the whole point of this projection. FIRE portfolio assumed at standard level for a couple [Zurich FIRE, Midland FIRE]. Their entire wealth is assumed to be in a brokerage account invested in a global ETF with low fees. I know that is not even remotely realistic but this assumption makes the projection much simpler to calculate. Otherwise there would need to be a lot more spreadsheets… |
| 2 | Annual dividend income is assumed to be 2% of the portfolio. It could be higher in some case but this is a good estimate because even a 2.5% dividend return is likely to be reduced overall to 2% due to portfolio management fees charged by investment firms. |
| 3 | The inflation adjusted capital gain from the sale of stock is assumed to be 400 percent of the initial investment (see item 11). This is likely a valid assumption for a global ETF held for 20 years but obviously is just an estimate as the stock performance will vary significantly depending on purchase price, market conditions, type of investment, and duration the stock was held. |
| 5 CH | The Zurich couple is assumed to not have any children or officially declared religious affiliations. I have attached to this post a PDF with the details of the estimated federal and cantonal level taxes for the Zurich based couple. Each spouse is assumed to have an equal amount of dividends (CHF 25,124). See PDF attachment for detailed Zurich tax estimate. [Official Swiss tax estimate calculator, Taxes on Swiss dividends] |
| 5 USA | Married couples have the choice in the US to file their taxes separately or jointly. The Midland couple is assumed to use the tax filing status “married filing jointly” and be within the 0% capital gains and qualified dividends bracket. [Taxes on USA dividend income] |
| 6 USA | There is no wealth tax in the United States. [What is a wealth tax?] |
| 7 CH | There is no capital gains tax in Switzerland. |
| 7 USA | Taxable income is in the 0% percent federal capital gains tax bracket for married couples filing jointly with annual incomes under $98,900 in the year 2026. [Capital Gains Tax in Michigan] |
| 8 CH | There is no canton capital gains tax for the canton of Zurich in Switzerland. |
| 8 USA | Some states in the USA do not have a capital gains tax but Michigan does. The US state of Michigan has a 4.25% flat income tax on all income including capital gains. Michigan allows a $5,800 exemption per person so the taxable income in item 4 so was reduced by $11,600 (for a couple) before applying the 4.25% state flat income tax. [Michigan tax rates and exemptions] |
| 9 CH | Switzerland requires AHV (government pension) contributions even for non-employed people living in the country. Those with substantial assets like the couple in this scenario pay a hefty annual bill. It is assumed they split their assets equally (each would be considered to be in the CHF 1,250,000 bracket). [Page 6 of Non-employed AHV contributions] |
| 9 USA | Non-employed people with only dividend and capital gains income in the US do not pay Social Security (government pension) contributions. [Social Security Benefits Planner] |
Conclusions
- This projection indicates that the Zurich couple will either need to decrease their annual budget by about 18% or increase their FI number.
- The Midland couple will also need to slightly reduce their annual budget (or increase their FI number) but only by a small amount because their annual tax liability is about 3%.
What about government pensions?
AHV pension income for the Zurich couple and Social Security income for the Midland couple were deliberately excluded from this projection.
Unfortunately the government pension schemes in many countries including Switzerland and the USA are already facing severe deficits and will need major reforms in the upcoming years to pay pension liabilities for their large aging populations.
I believe that it highly probable that Switzerland, the USA, and many other countries will be forced to implement an assets test for old age pensions. Australia has already implemented an assets test. By definition most financially independent people are millionaires and their high assets will make them ineligible to receive government pensions.
Some people in the USA financial independence community completely ignore the possibility of receiving Social Security payments when they reach traditional retirement age. They just assume their assets will make them ineligible.
It would be prudent in my opinion for financially independent Swiss people to not consider AHV payments as part of their FIRE numbers because probably in 20 years they will not be eligible anyways. I view my AHV wage deductions as a tax that supports elderly Swiss retirees but definitely not something that I will ever get any benefit from.
Attachments
Last edited: